
Commercial Real Estate Loans · Licensed in NJ, CT & FL · NMLS #1630225
Commercial Real Estate Loans — Financing to Buy or Refinance Income Property
Commercial real estate loans let you buy or refinance income-producing property — apartment buildings, mixed-use, retail, office, industrial, self-storage. The property’s income does most of the qualifying, so the deal has to work on its own numbers before anything about you matters. Mortgage-World.com (NMLS #1630225) is a licensed mortgage broker in New Jersey, Connecticut, and Florida.
Last updated September 2026 · reviewed by a licensed mortgage broker
Commercial
By Property Type
Its Own Income
Is Commercial
Commercial Real Estate Loans
What Is a Commercial Real Estate Loan?
A commercial real estate loan is financing used to buy, refinance, or cash out an income-producing property rather than a primary residence. The property itself is the collateral, and its ability to generate income is central to approval. Because these loans are underwritten on the numbers of the deal — the rents, the expenses, and the value — they work differently from the home loan you may be used to, and the right structure depends on the property type and your goals.
Commercial property is financed through several channels — bank programs, private capital, and agency options like Freddie Mac Multifamily for apartment buildings. Which one fits depends on the property type, its income, and whether you are buying or refinancing. Acquiring your first small apartment building and refinancing a retail center out of a maturing loan are different problems, and they do not always land in the same place.
Property Types
Commercial Property We Finance
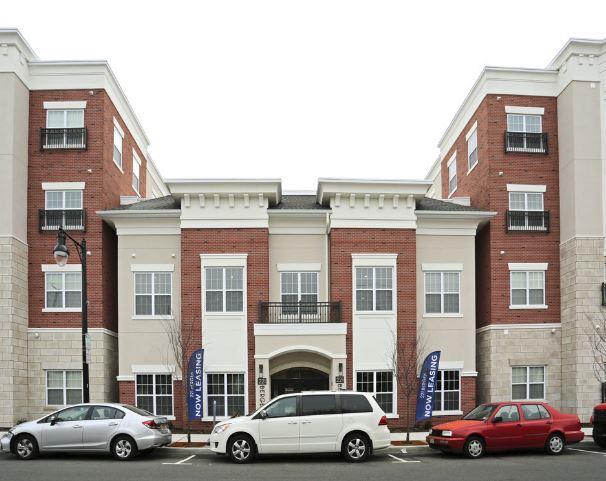
Commercial real estate loans cover a wide range of income property. The most common types we place include:
| Property Type | Examples |
|---|---|
| Multifamily / Apartments | 5+ unit apartment buildings, portfolios |
| Mixed-Use | Retail or office on the ground floor with apartments above |
| Retail | Strip centers, single-tenant retail, shopping complexes |
| Office | Professional and medical office buildings |
| Industrial | Warehouses, flex space, light industrial |
| Self-Storage | Storage facilities and portfolios |
| Specialty | Mobile home parks, student housing, hospitality, restaurants |
If your property produces income and isn’t your primary home, there is almost always a commercial or investment program that fits — including 1–4 unit rentals, which can often be financed with a DSCR loan.
How It Works
How Commercial Loan Qualifying Is Different
The biggest surprise for first-time commercial borrowers is how much the property matters compared to the borrower. A few key differences from residential lending:
The property’s income qualifies the loan
Lenders look at the property’s net operating income against the loan payment — the debt-service coverage ratio (DSCR). A property that comfortably covers its own payment is the foundation of approval.
Loan-to-value is typically lower
Commercial loans generally require a larger down payment than a home loan, so plan on more equity in the deal. The exact figure depends on the property type, its income, and the program.
Terms are structured differently
Commercial loans often carry shorter fixed terms with a balloon or reset, and some amortize over a longer schedule than the term itself. We walk you through the structure before you commit.
Your experience and reserves count
Lenders also weigh your credit, liquidity, reserves, and track record as an owner or operator — especially on larger or specialty properties.
Ways to Finance Commercial Property

Before You Start
What Happens After You Apply
- You send the application
A few minutes online. No documents at this stage.
- A licensed loan officer calls you
Someone on our team covering your state.
- We ask for documents and pull credit
Only once you have decided to move forward.
- You get an approval to shop with
Typically back within the hour.
FAQ
Commercial Real Estate Loan FAQ
Related Resources
Which Route Fits the Property?
 Mortgage-World.com
Start with three questions
No credit pull, no documents yet.
Your answers carry over — you won’t be asked twice.
★★★★★Google reviews
- Licensed in
- NJ · CT · FL
- Broker license
- NMLS #1630225
- Florida license
- MLB 1987
- Family owned since
- 2017
- Office
- Ridgefield, NJ
Send us the deal, not your life story
Property type, purchase price or current value, and the rents it collects. That is enough for a licensed loan officer to tell you whether it pencils and roughly what structure fits.
Written and reviewed by Chris Luis, Broker/Owner of Mortgage-World.com, NMLS #1630225. About the author